 how-to
How to Stop Foreclosure Fast: A 24-Hour Action Plan
Table of Contents
- Act Within 24 Hours: Your First Steps to Stop Foreclosure Fast
- Ways to Prevent Foreclosure: Explore All Your Options
- Mortgage Loan Modification: The Most Common Relief Path
- Last-Minute Strategies to Stop Foreclosure When Time Is Critical
- How to Stop Second Mortgage Foreclosure
- Find a HUD-Approved Housing Counselor and Seek Help Early
- Avoid Foreclosure Rescue Scams and Verify Legitimacy
- Respond to Foreclosure Notices and Legal Documents
- Frequently Asked Questions
Last Updated: October 18, 2026
Act Within 24 Hours: Your First Steps to Stop Foreclosure Fast
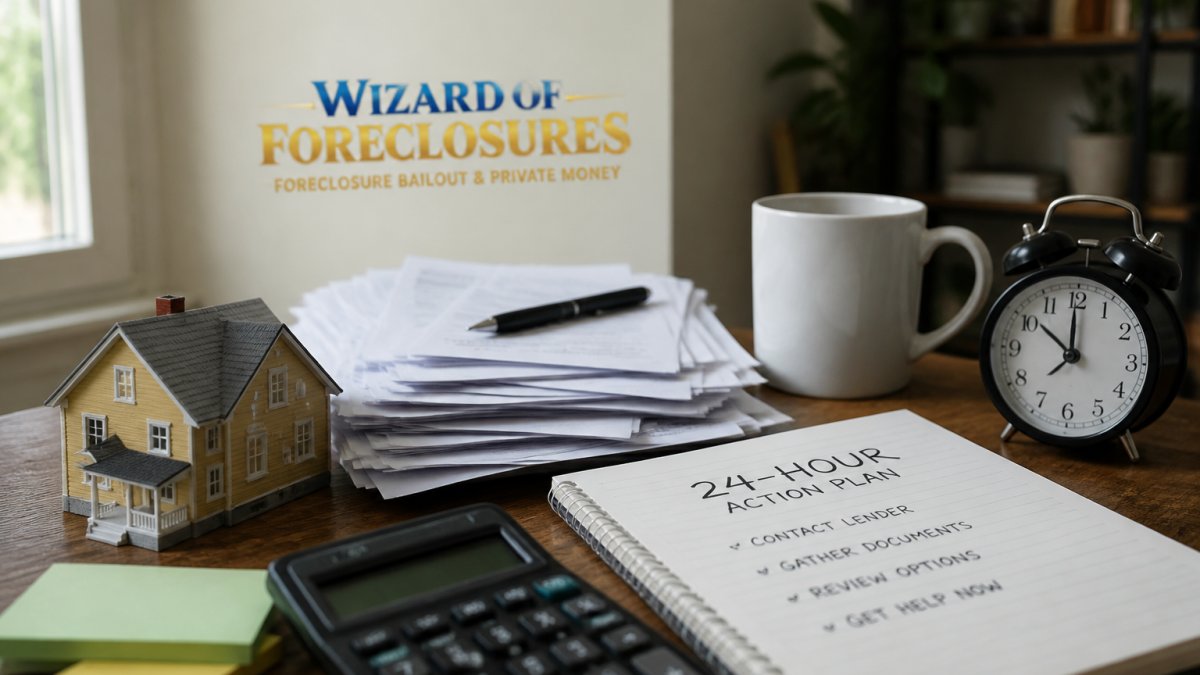
Foreclosure doesn't happen overnight, but the clock starts ticking the moment you miss a payment. Here's what matters most in the next day.
Contact Your Mortgage Lender or Servicer Immediately
Most homeowners delay this call out of embarrassment, but your servicer can't help if they don't know you're struggling.
When you call:
- Explain your situation clearly: job loss, medical emergency, income reduction
- Ask about loss mitigation options available to you
- Request a temporary pause while you gather documents
Write down everything and get confirmation numbers; documentation protects you.
Gather Your Financial Documents
To stop foreclosure fast, you need proof of your financial situation; servicers won't modify your loan without it.
Pull together these documents today:
- Last two months of pay stubs
- Last two years of tax returns
- Recent bank statements (last 30 days)
Don't wait for perfection. Gather what you have; missing documents can be added later, but delay costs time.
Prioritize by Foreclosure Stage, Not by Panic
The biggest first-24-hour mistake is treating every task as equally urgent. Your first move depends on your foreclosure stage.
Stage 1: You missed a payment but no formal notice has arrived.
- Call the loss mitigation department today, not general customer service.
- Request the application package in writing (email is fine).
- Ask whether and when the missed payment is reported to credit bureaus.
Stage 2: You received a notice of default, breach letter, or acceleration notice.
- Write down every deadline and the cure amount (total needed to reinstate).
- Call the servicer within 24 hours and confirm receipt of the notice.
- Submit a complete loss mitigation application fast; federal servicing rules generally require evaluation of a complete application received before certain foreclosure milestones.
Stage 3: A foreclosure sale date has been scheduled.
- Confirm the sale date, time, and location in writing with the servicer or trustee.
- Ask whether any loss mitigation application is pending and whether the sale will be postponed.
- Explore emergency options below (bridge financing, short sale, deed in lieu, bankruptcy consultation).
What Not to Do in the First 24 Hours
- Do not ignore the notice or assume the servicer will call you.
- Do not move out of the home; occupancy can affect your options and legal standing.
- Do not sign documents you don't understand, especially anything labeled a deed or transfer.
Documents to Have Ready Before You Call
Have ready: your loan number and property address, most recent mortgage statement, last two pay stubs, a one-paragraph hardship explanation with dates, a rough monthly budget, and any notices. If you don't have everything, call anyway; the servicer can start intake and tell you what's missing.
Ways to Prevent Foreclosure: Explore All Your Options
You have more choices than you think. Understanding them now helps you pick the right path.
Loss Mitigation Options at a Glance
Loss mitigation means working with your servicer on a solution that keeps you in your home. The main paths:
Loan Modification, Change your mortgage terms: lower rate, longer term, or missed payments added to the end. The most common and often most sustainable solution.
Forbearance Agreement, Pause or reduce payments for 3-12 months during hardship.
Refinancing, Replace your loan with better terms.
Short Sale, Sell for less than you owe with lender approval; the servicer forgives the difference.
Deed in Lieu of Foreclosure, Transfer the home to the lender instead of foreclosing.
Bankruptcy, File Chapter 7 or 13 to halt foreclosure while reorganizing debt.
Your income, equity, and hardship reason determine what's realistic.
Compare Options Side by Side
Use this comparison to narrow the field before calling your servicer. Eligibility and timing vary by investor, loan type, and state, so treat it as a starting point, not a guarantee.
| Option | Typical eligibility signals | Typical timeline | Credit impact | Key tradeoff |
|---|---|---|---|---|
| Loan modification | Documented hardship, stable or recoverable income, affordability gap | 3-6 months including trial payments | Can be neutral to moderately negative depending on reporting | Lowest payment, but you stay in the home and the loan term may extend |
| Forbearance | Temporary hardship with a clear recovery date | Days to weeks to approve; 3-12 months of relief | Depends on servicer reporting; missed payments may still report | Payments resume later; you may need a repayment plan or modification at the end |
| Repayment plan | Hardship is over and you can afford a higher payment | Weeks | Missed payments already reported; plan itself may not add damage | Catch-up payment is higher; defaulting on the plan restarts the clock |
| Refinance | Equity, decent credit, verifiable income | 30-60 days | A hard inquiry and new account; can improve score over time | Closing costs and higher rates if credit is damaged |
| Short sale | Underwater or near-underwater home, documented hardship | 3-6 months | Less damaging than foreclosure in most scoring models | You lose the home and may owe taxes on forgiven debt unless excluded |
| Deed in lieu | Cannot afford the home, servicer agrees to accept the deed | 4-8 weeks | Similar to short sale, generally less than foreclosure | You lose the home and may still owe on a second lien or forgiven debt |
| Chapter 13 bankruptcy | Regular income, need to cure arrears over time | Filing is immediate; plan runs 3-5 years | Severe and long-lasting | Court supervision and legal fees; protects the home only if you complete the plan |
| Chapter 7 bankruptcy | Income below state median or unable to pay debts | Filing is immediate; discharge in a few months | Severe and long-lasting | Does not by itself cure mortgage arrears; the home may still be at risk |
Which Option Fits Your Situation?
- Temporary setback, income is back: Ask about a repayment plan or short forbearance with a clear exit plan.
- Income is lower permanently: Ask about a loan modification first; it targets long-term affordability gaps.
- Equity but damaged credit: Explore refinancing or, if the sale is imminent, equity-based bridge financing below.
Documents That Speed Up Every Option
Servicers use the same core package for most options: a completed Uniform Loan Modification Application (ULMA) or equivalent, two months of pay stubs, two years of tax returns, 30 days of bank statements, a hardship letter with dates, a monthly budget, and proof of hardship. Submit what you have and add missing pieces quickly rather than delaying.
Questions to Ask Your Servicer About Each Option
- What is the deadline to submit a complete application before the next foreclosure milestone?
- Will the foreclosure sale be postponed while my application is reviewed?
- What is the trial payment amount and how many payments are required?
Write down the answers and the representative's name. A HUD-approved housing counselor can review any option with you at no cost.
Mortgage Loan Modification: The Most Common Relief Path
Loan modification is the most frequently approved option because it benefits both sides: you get affordable payments and the servicer gets paid instead of absorbing foreclosure costs.
How Loan Modification Works
A loan modification changes your loan terms to make payments affordable. The servicer reviews your income and expenses, then offers new terms. The process:
- Submit a complete application with all financial documents
- Servicer reviews your situation and calculates a sustainable payment
- Trial period begins, usually three months of modified payments
- You make trial payments on time to prove you can handle the new amount
- Permanent modification is granted if trial period succeeds
- New loan documents are signed and the modification is permanent
The process typically takes 3-6 months, and foreclosure is often suspended while your application is under review.
What You Need to Apply
Servicers use the same documents for all loss mitigation options:
- Completed Uniform Loan Modification Application (ULMA)
- Two months of pay stubs for all household earners
- Two years of federal tax returns
Missing information delays approval. Submit what you have and add missing pieces quickly.
Last-Minute Strategies to Stop Foreclosure When Time Is Critical
If your foreclosure sale is weeks or days away, standard loss mitigation moves too slowly. You need emergency funding or an immediate alternative.
Emergency Refinancing and Bridge Loans
When traditional refinancing won't work, equity-based private lending can provide fast capital to pay off arrears and stop the foreclosure. Private money and bridge loans move faster than bank loans because they're based on equity, not credit or employment, so funding can happen in days.
This approach works best if:
- You have at least 20% equity in the home
- The foreclosure sale is imminent
- You have a plan to refinance or sell within 6-12 months
The trade-off is higher rates and fees, but stopping foreclosure is worth it when the alternative is losing the home.
Short Sale or Deed in Lieu of Foreclosure
If you can't afford to keep the home even with modifications, a short sale or deed in lieu lets you exit without a foreclosure judgment.
A short sale sells the home for less than you owe, with the servicer's written approval to forgive the difference; it takes 3-6 months and damages credit. A deed in lieu transfers ownership directly to the lender; it's faster (4-8 weeks) but you have no say in the outcome.
How to Stop Second Mortgage Foreclosure
Second mortgages and home equity lines of credit (HELOCs) can also be foreclosed. Because second-lien holders sit behind the first mortgage and are often wiped out in a first-lien foreclosure, they're motivated to work with you.
Contact your second mortgage servicer immediately. Ask about:
- Payment reduction or modification
- Forbearance
- Short sale approval (easier with second liens)
Many second-lien holders negotiate aggressively to avoid losing their position. Use that to your advantage.
Find a HUD-Approved Housing Counselor and Seek Help Early
A HUD-approved housing counselor provides free guidance on foreclosure prevention, understands loss mitigation, and can help prepare applications. Find one via the HUD counselor locator tool, the HUD hotline at 1-800-569-4287, or a local nonprofit housing organization. Counselors aren't lenders selling you something. Contact one immediately after you miss a payment; early help expands your options significantly.
Avoid Foreclosure Rescue Scams and Verify Legitimacy
Scammers target desperate homeowners, promising to stop foreclosure fast for upfront fees. By the time you realize you've been defrauded, your money is gone and foreclosure has progressed.
Red flags for scams:
- Demand for upfront fees before any work is done
- Promises to stop foreclosure guaranteed
- Pressure to sign documents you don't understand
Legitimate help never charges upfront: HUD counselors are free, modification companies charge only after approval, and attorneys bill hourly or on contingency. Verify any company through the Better Business Bureau, your state attorney general's office, references, and licensing, and get everything in writing.
Respond to Foreclosure Notices and Legal Documents
Foreclosure notices are legal documents; ignoring them makes things worse.
Foreclosure moves fast, but you can move faster. Contact your servicer, gather your documents, and reach out to a housing counselor; these three steps open doors that close quickly once foreclosure accelerates.
When standard loss mitigation options don't move fast enough, Bailout Capital provides emergency capital to stop foreclosure through equity-based private lending and bridge financing.
Frequently Asked Questions
What should I do first if I receive a foreclosure notice?
Contact your mortgage servicer immediately, do not delay. Request a complete breakdown of what you owe, including principal, interest, fees, and late charges. Ask about loss mitigation options, such as loan modification or forbearance. Gather all mortgage documents and recent bank statements. Consider reaching out to a HUD-approved housing counselor for free guidance. Acting within the first few days after receiving notice is critical to stop foreclosure fast and preserve your options.
Can mortgage loan modification help me avoid foreclosure?
Yes. Mortgage loan modification restructures your loan terms, extending the repayment period, reducing the interest rate, or capitalizing missed payments, to make your monthly payment affordable. It is one of the most common ways to prevent foreclosure. You must demonstrate financial hardship and prove you can afford the modified payment. Contact your lender to request a modification application and submit required documents, including pay stubs, tax returns, and a hardship letter explaining your circumstances.
How can I stop a second mortgage foreclosure?
Contact the second mortgage servicer immediately and ask about loss mitigation options specific to second mortgages, which typically include loan modification or forbearance. A second mortgage foreclosure can occur even if your first mortgage is current. Respond promptly to all legal notices. If you cannot modify the second mortgage, consider refinancing the first mortgage to pay off the second, or explore a short sale if both mortgages are underwater. Seek guidance from a HUD-approved counselor to evaluate your specific situation.
How do I know if a foreclosure assistance company is legitimate?
Verify that any lender or counselor is HUD-approved (for nonprofits) or licensed in your state. Legitimate lenders do not charge upfront fees before providing a loan. Check for state licensing through your attorney general's office and verify company registration. Be wary of guarantees that foreclosure can be stopped or promises of loan forgiveness. Ask for references and check online reviews from verified customers. If a company pressures you to sign documents quickly or requests payment before funding, it is likely a scam.