 blog
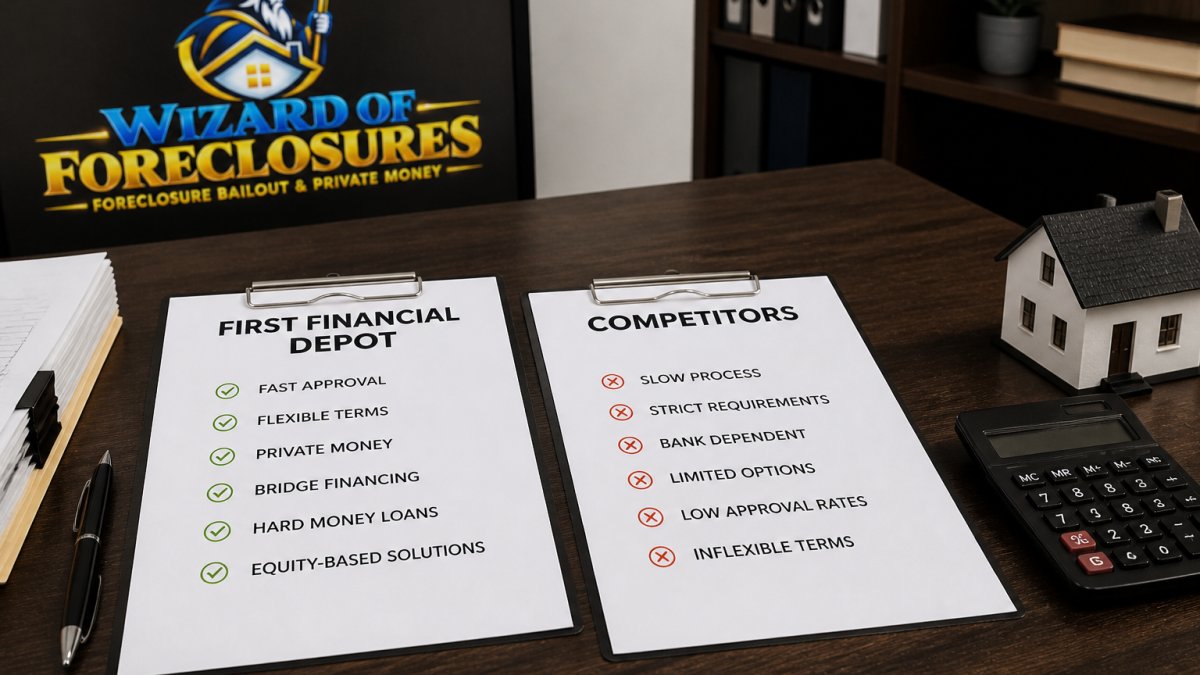
First Financial Depot vs Competitors: 2026
Last Updated: October 23, 2026
Quick Summary
First Financial Depot vs competitors differs primarily in underwriting criteria, fee structures, and term flexibility rather than published rates. When comparing lenders, request the same five data points from each: rate range, origination points, total closing costs, maximum LTV, and prepayment terms to determine true all-in cost over your expected hold period.
- Hard money terms commonly run 6 to 36 months, usually interest-only with a balloon at maturity, though term options vary by lender.
- Underwriting levers that vary most between lenders include credit floor, income documentation requirements, experience requirements, and property eligibility criteria.
- All-in cost includes the note rate plus origination points plus third-party costs plus extension or prepayment charges, annualized over your actual holding period.
- Request written confirmation of points, closing costs, extension fees, and prepayment terms before committing, as most terms are quote-based and deal-specific.
- Hard money lenders typically confirm interest rate range, origination points, prepayment penalty structure, and maximum LTV upfront, but keep exact rates and fees quote-only.
Table of Contents
- What Hard Money Loans Are and Why Speed Matters
- First Financial Depot Loan Rates and Terms Explained
- Hard Money Loan Approval Requirements: What Lenders Actually Check
- Bridge Loan vs Hard Money Loan: Which Solves Your Problem
- Hard Money Loan Risks and How to Protect Yourself
- How Bailout Capital Differs from Other Private Lenders
- Choosing the Right Lender for Your Situation
- Frequently Asked Questions
What Hard Money Loans Are and Why Speed Matters
A hard money loan is short-term financing secured by real estate collateral, typically from private lenders rather than banks. These loans prioritize speed and flexibility over credit scores, making them essential for time-sensitive situations like foreclosure or urgent property acquisition.
When evaluating First Financial Depot vs competitors, understand that private lenders focus on the property's value and your equity position rather than personal creditworthiness.
When traditional banks say no, hard money lenders say yes if the collateral supports it, filling a critical gap for borrowers with low credit, recent bankruptcy, or simply no time to wait.
First Financial Depot Loan Rates and Terms Explained
What is typically confirmed up front
- The interest rate range the lender is willing to quote for your property type and LTV band.
- The origination points (usually expressed as a percentage of the loan amount).
- Whether there is a prepayment penalty and how it is calculated.
- The maximum LTV and maximum loan amount for the product.
What is almost always quote-only
- The exact rate inside the quoted range.
- Underwriting, appraisal, and processing fees.
- Whether fees are financed into the loan or paid at closing.
- Extension fees if the project runs long.
What you should treat as unknown until you have it in writing
- Any 'teaser' rate that disappears after the first payment.
- Draw schedules and inspection fees on renovation loans.
- Servicing transfer terms.
To compare First Financial Depot against competitors, request the same five data points from every lender for the same hypothetical deal: rate range, origination points, total closing costs, maximum LTV, and prepayment terms. A lender who won't put those in writing has told you something.
The fee structure that actually drives total cost
All-in cost is the note rate plus origination points plus third-party costs plus extension or prepayment charges, annualized over your actual holding period.
Terms and repayment structures
Hard money terms commonly run 6 to 36 months, usually interest-only with a balloon at maturity; some lenders offer partial principal paydown or longer terms for stabilized assets.
For a side-by-side look at how another lender structures its terms, see Growth Funding Group vs First Financial: 2026 lender comparison.
Hard money lenders vary significantly in what they confirm upfront versus what remains quote-only or unknown until closing.
| Information Type | Typically Confirmed | Status |
|---|---|---|
| Interest rate range | Yes | Depends on LTV and property type |
| Origination points | Yes | Usually expressed as percentage of loan |
| Prepayment penalty | Yes | Structure confirmed upfront |
| Exact rate inside range | No | Quote-only |
| Underwriting and appraisal fees | No | Quote-only |
| Extension fees | No | Unknown until in writing |
| Teaser rates | No | Treat as unknown until written |
| Draw schedules on renovation loans | No | Unknown until in writing |
Hard Money Loan Approval Requirements: What Lenders Actually Check
Hard money underwriting is asset-based, but that doesn't mean no criteria. Lenders differ sharply on credit floors, documentation, experience, and property eligibility, and those differences determine whether you get approved. When comparing First Financial Depot vs competitors, focus on underwriting boxes, not just rates.
The four underwriting levers that vary most between lenders
- Credit floor. Some lenders publish a minimum FICO (often in the 550-620 range for investor loans); others have no stated floor and underwrite the deal instead. Ask each lender for its stated minimum and whether exceptions are possible with compensating factors such as strong equity or experience.
- Income documentation. Stated-income underwriting is common in hard money, but not universal. Some lenders require bank statements or tax returns above certain loan amounts. If you are self-employed or have irregular income, this is the first question to ask.
- Experience requirements. Many lenders require at least one completed project of the same type for fix-and-flip or ground-up loans. First-time investors may face lower LTV caps or higher reserves. Ask whether the lender counts prior rentals, flips, or construction experience, and how it verifies them.
- Property criteria. Eligible property types, condition standards, and whether owner-occupied or second-lien requests are accepted vary widely. A lender that funds non-owner-occupied investor properties may not fund a primary residence, and vice versa.
What the file actually needs to clear underwriting
- A current valuation or appraisal supporting the after-repair value (ARV) for renovation deals.
- A written scope of work and budget for construction or rehab loans.
- Proof of liquidity or reserves, commonly several months of payments plus a contingency.
- A credible exit strategy: sale, refinance, or rental stabilization, with a timeline.
- Entity documents if borrowing through an LLC.
Matching borrower scenarios to lender fit
- Fix-and-flip investor: prioritize lenders with construction draw experience, ARV-based underwriting, and extension options. Ask how draws are inspected and funded.
- Second-lien or cash-out borrower: confirm the lender offers subordinate financing and how it coordinates with the first mortgage holder.
- Borrower with credit challenges: ask for the stated credit floor and whether exceptions are considered; get any exception in the term sheet.
- Borrower prioritizing speed and flexible documentation: ask which documents are truly required versus requested, and get the closing timeline in writing.
These aren't recommendations of one lender over another, they're the questions that reveal which underwriting box your deal fits. A deal that clears one lender may be declined by another for reasons unrelated to the property's value.
Do not assume a lender's published 'minimum requirements' are the full story. Underwriting exceptions exist, but they are discretionary. Get any exception, credit, LTV, experience, documented in the term sheet before you pay for an appraisal.
For guidance on vetting a lender's licensing and track record, see how to verify legitimate private lenders in 2026.
Bridge Loan vs Hard Money Loan: Which Solves Your Problem
Bridge financing and hard money loans are sometimes used interchangeably, but they serve different purposes and have different structures.
A bridge loan bridges the gap between two transactions, buying a new property before selling your current one, or covering the timing gap between a foreclosure notice and a refinance closing. Terms are typically 3-12 months, focused on the exit event that repays the loan.
Hard money loans are broader asset-based products funding acquisition, renovation, cash-out refinancing, or any situation where a property secures the loan.
Facing foreclosure in 90 days? Bridge financing might get you to a refinance closing. Acquiring a distressed property that needs renovation before resale? Hard money provides the capital and timeline flexibility.
The key difference: bridge loans solve timing problems between two known events; hard money loans solve capital problems when traditional lending won't work. For most distressed property situations, hard money is the broader, more flexible solution.
For a detailed comparison of these options, see bridge loans vs hard money loans: key differences.
Hard Money Loan Risks and How to Protect Yourself
Hard money loans carry real risks. Learn about the specific risks involved in hard money lending and how to protect yourself Understanding them before signing lets you protect yourself from worse outcomes.
The most obvious risk is cost: higher rates and fees mean a much larger repayment obligation than a conventional mortgage.
Default risk is real. If you can't make payments or your exit strategy fails, the lender forecloses and takes the property.
Valuation risk matters too. Appraisals can be wrong, especially on distressed or heavily renovated properties.
Predatory lending is a genuine concern: some lenders exploit desperate borrowers with unreasonable terms, hidden fees, or structures designed to trap you in perpetual refinancing.
To protect yourself: get everything in writing, have an attorney review loan documents, ensure you have realistic exit strategies, maintain cash reserves, and work with established lenders who have verifiable track records.
How Bailout Capital Differs from Other Private Lenders
Bailout Capital approaches distressed lending differently: we see your situation as a problem to solve, not a transaction, and we move with urgency because we understand the stakes.
Speed is our defining feature: funding in 48-72 hours, because foreclosure timelines don't wait. Direct capital from decision-makers who understand your situation.
Our equity-based lending model means we focus on what matters: your property value and your stake in it.
At Bailout Capital, you work directly with our team, we explain every step, answer questions honestly, and help you understand exactly what you're committing to.
Many hard money borrowers make the mistake of working with the first lender who says yes. Comparing terms, fees, and lender reliability across multiple options typically saves thousands of dollars and prevents worse outcomes down the road.
Choosing the Right Lender for Your Situation
Selecting the right hard money lender is one of the most important financial decisions you'll make during a crisis.
Start by verifying legitimacy.
Compare actual terms, not promises. Get quotes from multiple lenders showing rates, fees, LTV limits, and repayment structures, for the same loan amount, property type, and timeline.
Evaluate the lender's experience with your specific situation. If you're a real estate investor needing fix-and-flip capital, work with lenders who regularly fund renovations and understand exit strategies.
Consider the relationship, not just the transaction.
For detailed guidance on vetting lenders, see how to verify legitimate private lenders in 2026.
When you're facing foreclosure or need capital fast, choosing the right lender determines whether you save your property or lose it.
Frequently Asked Questions
How risky is hard money lending for borrowers?
Hard money loans carry higher risk than traditional mortgages because they prioritize collateral over credit history, feature shorter terms (typically 1-3 years), and charge higher interest rates. If you cannot repay or refinance before the term ends, the lender can foreclose on the property. The real risk depends on your exit strategy: investors flipping properties or refinancing into conventional loans face lower risk than those counting on property appreciation alone. Understanding your ability to repay or refinance is critical before accepting these terms.
What are the main hard money loan approval requirements?
Hard money lenders focus on property value and equity rather than credit scores. Most require a minimum down payment or equity position (often 20-30%), proof of funds or liquidity, and a clear exit strategy showing how you'll repay. Credit score requirements are flexible, many lenders work with borrowers who have past bankruptcies or low FICO scores. Property type and condition matter: single-family homes, multifamily buildings, and investment properties are standard, but the property must have sufficient equity to secure the loan.
How does a bridge loan differ from a hard money loan?
A bridge loan is short-term financing (typically 6-12 months) designed to bridge the gap between buying a new property and selling an existing one. A hard money loan is broader asset-based lending that funds property acquisition, renovation, or refinancing and typically runs 1-3 years. Bridge loans assume you'll sell a current property to repay; hard money loans assume you'll refinance, sell, or generate cash flow. Both bypass traditional underwriting, but bridge loans are narrower in purpose while hard money loans serve multiple real estate strategies.
What should I compare when choosing between hard money lenders?
Compare funding speed (how quickly capital closes), loan-to-value ratio (how much they'll lend against property value), interest rates and origination fees, loan term length, prepayment penalties, and approval requirements. Ask about their experience with your property type and whether they service loans or sell them. Request references from recent borrowers. Verify they're licensed and check for complaints with your state's financial regulator. Transparency about fees and terms separates legitimate lenders from predatory ones.